
⏱ Estimated reading time: 18 min read
You have a steady income, a deposit ready and an investment property in mind. You’ve calculated the expected mortgage repayments, considered the rental income and believe the purchase should fit comfortably within your finances.
Then you approach a lender and discover that your borrowing capacity is lower than expected.
It’s a situation that can surprise Australian property investors, particularly those who already own a home or have an existing investment property.
The reason often comes down to loan serviceability.
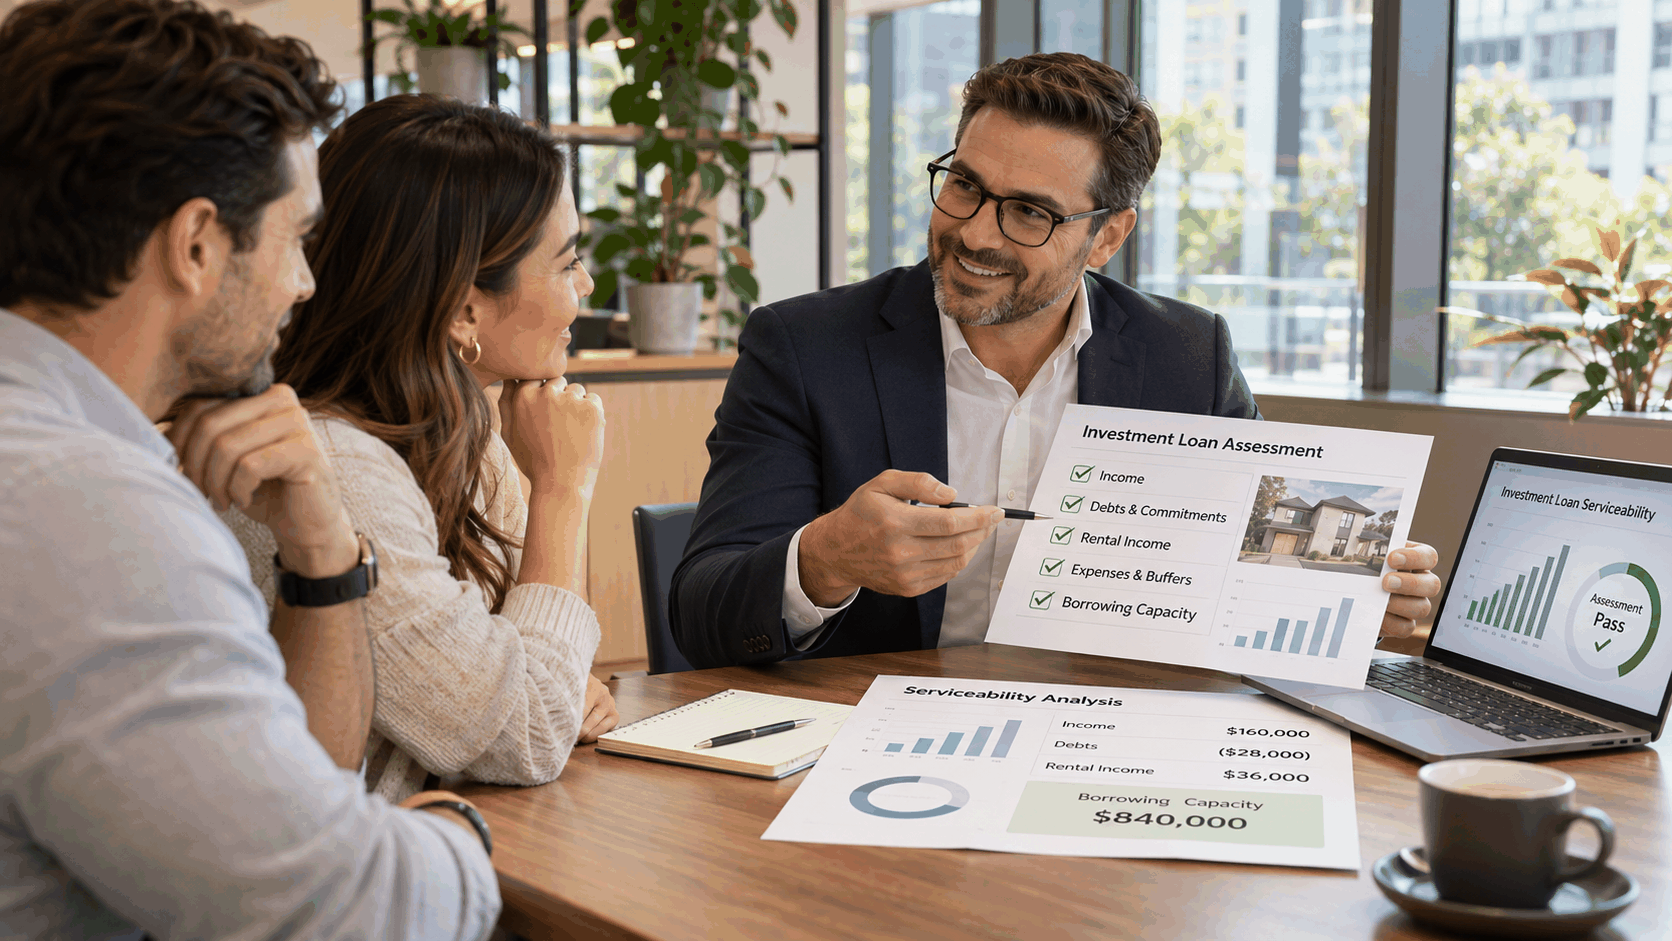
When assessing an investment property loan, lenders don’t simply check whether your income is sufficient to cover repayments at the advertised interest rate.
They examine your existing debts, household expenses, employment income, rental income and ability to manage repayments under different financial conditions.
And not every lender uses exactly the same assessment method.
Understanding how investment loan serviceability works can help you establish a realistic borrowing budget, prepare your application and identify financing options that may suit your circumstances.
In this guide, we’ll explain what Australian lenders look for, how rental income is assessed and why borrowing capacity can vary between lenders.
What Is Investment Loan Serviceability?
Investment loan serviceability is a lender’s assessment of your ability to repay a proposed investment property loan while continuing to meet your existing financial commitments.
It helps the lender determine whether the additional borrowing is manageable under its credit assessment requirements.
The assessment typically considers:
- Employment and other acceptable income
- Expected rental income from investment properties
- Existing mortgage repayments
- Credit cards and personal loans
- Household living expenses
- Dependants and other financial commitments
- The proposed investment loan
- Interest rate assessment requirements
Lenders use this information to estimate whether sufficient income remains after accounting for expenses and debt obligations.
This is sometimes expressed through a net income surplus calculation.
A positive result may indicate that the proposed loan satisfies the lender’s serviceability requirements.
However, serviceability is only one part of the lending decision. Credit history, property valuation, loan to value ratio and other policies may also affect approval.
How Do Banks Calculate Investment Loan Serviceability?
Although assessment methods vary, most lenders follow a similar process.
First, they establish your acceptable income.
Next, they account for existing financial commitments and household expenditure.
They then assess the repayments associated with the proposed investment loan using their applicable interest rate and repayment assumptions.
The resulting calculation helps determine whether you have sufficient financial capacity to support the borrowing.
The Basic Serviceability Calculation
A simplified way to understand the process is:
Assessable income minus assessed living expenses and debt repayments equals net income surplus.
For example, consider a hypothetical investor with the following monthly figures.
| Assessment component | Monthly amount |
|---|---|
| Assessable income after applicable adjustments | $13,000 |
| Household living expenses | $4,500 |
| Assessed existing debt commitments | $3,500 |
| Assessed proposed investment loan repayment | $4,200 |
| Remaining net income surplus | $800 |
In this simplified example, the investor has $800 remaining after the assessed commitments.
However, a lender may require a particular surplus or apply additional criteria.
The example doesn’t represent a specific bank’s calculator. Actual calculations may involve gross to net income conversion, expense benchmarks, loan assessment floors and other policy adjustments.
It illustrates why lenders examine the complete financial picture rather than comparing rental income with the new mortgage repayment alone.
How Do Lenders Assess Rental Income?
Rental income is particularly important when applying for an investment property loan.
Most lenders recognise that a rental property can generate income that contributes towards borrowing costs.
However, they generally don’t include the full advertised rent in their serviceability calculations.
Instead, lenders often apply an adjustment known as rental income shading.
This helps account for potential vacancies, property expenses and fluctuations in rental income.
What Is Rental Income Shading?
Rental income shading means a lender recognises a percentage of the property’s eligible gross rental income rather than the full amount.
For example, a lender might use 80% of eligible rental income in its assessment.
Other lenders may use different percentages or methodologies.
APRA’s residential mortgage lending guidance indicates that prudent assessment policies should generally make appropriate allowances for rental income uncertainty and property related expenses.
Example: How Rental Income Shading Works
Suppose an investment property generates $700 per week in rent.
Annual gross rental income:
$700 × 52 = $36,400.
The following table shows how different illustrative assessment percentages affect the amount recognised.
| Rental income assessment | Annual assessable rent |
|---|---|
| 100% of gross rent | $36,400 |
| 90% of gross rent | $32,760 |
| 80% of gross rent | $29,120 |
| 75% of gross rent | $27,300 |
| 70% of gross rent | $25,480 |
A lender recognising 80% would include $29,120 rather than the full $36,400.
However, shading percentages shouldn’t be compared in isolation.
One lender may recognise a higher proportion of rental income while separately accounting for more property expenses.
Another might use a lower percentage but apply a different approach to ongoing expenses.
The overall calculation matters more than the percentage alone.
How Is Rental Income Verified?
For an existing investment property, lenders may request:
- Current lease agreements
- Rental statements
- Property management records
- Relevant bank statements
- Other acceptable evidence of rental income
For a property you’re planning to purchase, the lender may consider a rental appraisal prepared by an acceptable property professional.
Some lenders may have specific requirements for the age, source and format of the appraisal.
An optimistic rental estimate isn’t necessarily the figure the lender will accept.
This is why obtaining reliable rental information before applying for finance can be helpful.
How Employment Income Affects Borrowing Capacity
Employment income is generally a major component of a serviceability assessment.
However, lenders distinguish between different types of earnings.
A consistent base salary may be assessed differently from bonuses, commissions, overtime or business income.
Permanent Employment Income
For salaried employees, lenders commonly review recent payslips and other employment documentation.
They may verify your employment arrangements and assess whether the income is ongoing.
Overtime, Bonuses and Commissions
Variable income can fluctuate from month to month.
A lender may review historical earnings to establish whether that income is consistent and likely to continue.
For example, a professional earning a $120,000 base salary and an additional $30,000 in annual bonuses may not have the entire bonus amount recognised.
The lender may apply an adjustment or require evidence over a longer period.
Casual and Contract Employment
Casual and contract workers may also qualify for investment loans.
However, lenders may examine employment history, income consistency and the nature of the employment arrangement.
Self Employed Borrowers
Self employed applicants are generally assessed using business and personal financial information.
Depending on the lender, this may include tax returns, financial statements and evidence of sustainable income.
Lenders can differ in their treatment of depreciation, non recurring expenses and income changes between financial years.
For investors with variable or self employed earnings, understanding these requirements before applying can help avoid unexpected delays.
How Existing Mortgages Affect Investment Loan Serviceability
If you already have a home loan, the lender will include that commitment in its assessment.
This applies whether the existing property is your family home or another investment.
Importantly, the repayment used in the lender’s calculation may differ from the amount you’re currently paying.
Lenders may assess existing mortgage commitments using applicable interest rate buffers, repayment assumptions and remaining loan terms.
For example, your current mortgage repayment might be $2,800 per month.
A lender’s serviceability assessment could attribute a higher monthly repayment to that loan.
This doesn’t mean your actual repayment has increased.
It means the lender is assessing the commitment according to its lending requirements.
What If You Have Multiple Investment Properties?
Investors with several properties may have more complex applications.
The lender generally needs to consider the debts and eligible rental income associated with the existing portfolio.
A property generating positive rental cash flow doesn’t necessarily contribute an equivalent positive amount to lender serviceability.
Rental income adjustments and assessed loan repayments can produce a different result.
This is one reason experienced investors sometimes encounter borrowing restrictions despite owning properties with considerable equity.
Do Credit Cards Reduce Investment Borrowing Capacity?
Credit cards can affect serviceability even when you pay the balance in full every month.
Some lenders assess credit card commitments using the approved credit limit rather than the amount currently outstanding.
Consider a borrower with two credit cards.
Card A has a $15,000 limit.
Card B has a $10,000 limit.
The combined available credit limit is $25,000.
A lender may calculate an ongoing repayment commitment based on those limits, even if the actual balances are relatively small.
The precise calculation depends on lender policy.
Before applying for investment finance, review whether existing credit facilities are necessary.
Reducing unused limits may help in some circumstances, but it isn’t guaranteed to improve every application.
Any changes should be considered alongside your broader financial needs.
How Personal Loans, Car Finance and HELP Debt Are Treated
Mortgage serviceability assessments also consider other financial commitments.
These may include personal loans, vehicle finance, buy now pay later arrangements and education related repayment obligations.
An existing car loan can reduce the income available to support a new mortgage.
Likewise, a personal loan with substantial monthly repayments may affect the proposed investment borrowing amount.
For borrowers with a Higher Education Loan Program debt, lenders may consider the relevant repayment obligations when assessing income.
The treatment depends on the borrower’s circumstances and the lender’s policies.
It’s important to disclose relevant debts accurately.
A lender’s review is intended to establish the complete financial position, not simply the debts that appear most significant to the applicant.
How Lenders Assess Household Living Expenses
Your everyday spending also influences serviceability.
Australian lenders generally ask applicants to declare their regular living expenses.
These might include:
- Food and groceries
- Utilities and communications
- Transport
- Insurance
- Education and childcare
- Medical expenses
- Clothing and personal care
- Recreation
- Other regular household commitments
Lenders may compare declared expenses with applicable household expenditure benchmarks.
Where actual expenses exceed the relevant benchmark, the higher expenditure may affect the assessment.
Household composition also matters.
A single applicant with no dependants may have a different spending profile from a couple supporting several children.
Why Accurate Expense Reporting Matters
Understating expenses to obtain a larger loan can create problems.
A lender needs reliable information to assess whether the proposed borrowing is suitable.
More importantly, an inaccurate budget may result in financial commitments that are difficult to maintain.
Reviewing several months of actual transactions can help you prepare realistic figures.
Don’t overlook expenses paid quarterly or annually.
Insurance premiums, vehicle registration, school fees and other irregular costs should form part of your household budget.
What Is the Investment Loan Serviceability Buffer?
Australian lenders generally assess mortgage repayments using an interest rate higher than the actual loan rate.
This is known as a serviceability buffer.
The buffer helps determine whether borrowers could manage repayments if interest rates increased.
As of November 2026, APRA’s published minimum mortgage serviceability buffer for APRA regulated banks remains 3 percentage points.
For example, an investment loan carrying an interest rate of 6% would generally be assessed at no less than 9% under the standard buffer requirement.
The borrower isn’t charged 9% simply because the loan is assessed at that rate.
The higher rate is used to evaluate repayment capacity.
Example: Investment Loan Repayment Assessment
Consider a proposed $600,000 principal and interest investment loan over 30 years.
| Interest rate | Approximate monthly repayment |
|---|---|
| Actual loan rate of 6% | $3,597 |
| Illustrative assessment rate of 9% | $4,828 |
| Difference | $1,231 |
The lender may use approximately $4,828 as the repayment requirement in a simplified assessment based on these assumptions.
Actual lender calculations may differ depending on repayment terms, rate floors and other policies.
The difference helps explain why an investor who can comfortably meet repayments at the current rate may still qualify for less borrowing than expected.
For a practical examination of changing repayments, see our Interest Rate Stress Test for an Investment Property Loan guide.
What Is Debt to Income Ratio?
Debt to income ratio, commonly called DTI, compares relevant total debt with annual income under the applicable lending or reporting definition.
It’s another important consideration for investors carrying multiple mortgages.
A simplified calculation is:
Total debt divided by annual gross income.
For example, suppose a borrower has $900,000 in total relevant debt and annual gross income of $150,000.
The simplified DTI is six times.
This means the total debt equals six times the borrower’s annual income.
How Australia’s 2026 DTI Lending Limits Affect Investors
From February 2026, APRA introduced limits on the proportion of new mortgage lending that APRA regulated banks can provide to borrowers with DTI ratios of six times or more.
Under the announced settings, high DTI lending is limited to 20% of new owner occupied lending and 20% of new investor lending, measured separately.
This doesn’t mean an individual borrower is automatically prohibited from obtaining a loan above six times income.
However, the restrictions can influence lender appetite and policy for highly indebted borrowers.
Investors planning additional property purchases should therefore understand how their total borrowing compares with income.
The relevant DTI calculation may also differ from a simple personal estimate because regulatory reporting rules determine which debts and income are included.
Why Different Lenders Calculate Borrowing Capacity Differently
One of the most important points for property investors is that borrowing capacity isn’t identical across the lending market.
Lenders have different policies covering acceptable income, rental income adjustments, existing debts and expenses.
For example, consider two applicants with similar salaries.
One receives most income through a fixed salary.
The other earns a lower base salary with substantial commissions.
A lender that assesses commission income more conservatively may calculate different borrowing capacities for the two applicants.
The same applies to investors with existing rental properties.
Differences in the treatment of rental income and mortgage commitments may affect the final result.
Does the Lender Offering the Highest Borrowing Capacity Make the Best Choice?
Not necessarily.
Borrowing capacity is important, but it shouldn’t be the only factor.
Other considerations include:
- Interest rates
- Loan fees
- Repayment structure
- Offset account availability
- Refinancing flexibility
- Security arrangements
- Future borrowing objectives
A lender offering a larger amount may not provide the most suitable overall arrangement.
The objective is to find finance that meets your needs and remains manageable.
Example: Why an Investor May Be Approved for Less Than Expected
Consider a property investor earning $145,000 annually.
They own a family home with a $420,000 mortgage and want to purchase a rental property.
The proposed property is expected to generate $650 weekly rent.
The investor initially assumes the rent will largely cover the proposed investment mortgage.
However, the lender’s assessment may include several adjustments.
First, it may recognise only part of the proposed rental income.
Second, it may assess the existing mortgage using a repayment amount higher than the current payment.
Third, it will consider household living expenses and any other financial commitments.
Finally, it assesses the proposed investment loan using applicable serviceability requirements.
The combined effect can reduce the amount available to borrow.
The applicant may still qualify for finance, but the approved amount could be lower than their original estimate.
This is why obtaining an indicative borrowing assessment before committing to a purchase can be valuable.
Can You Improve Your Investment Loan Serviceability?
Some financial decisions can influence serviceability.
However, any changes should support your broader financial position rather than simply produce a larger borrowing estimate.
Review Existing Debts
Reducing high cost personal debt may improve household cash flow and lower assessed commitments.
Check Unused Credit Limits
Review whether existing credit facilities are necessary and how lenders may assess them.
Prepare Accurate Income Documentation
If you receive bonuses, commissions or business income, organised documentation may help lenders assess eligible earnings.
Review Your Household Budget
Understand your actual expenses and identify commitments that may no longer be necessary.
Obtain Reliable Rental Evidence
A current, credible rental appraisal may help establish the proposed property’s expected income.
Compare Suitable Lender Policies
Different lenders may assess your circumstances differently.
A finance broker can help explain those differences and identify lending options worth considering.
However, there is no guarantee that changing lenders or reducing a particular expense will result in additional borrowing approval.
What Documents Do Lenders Need for an Investment Loan?
Document requirements vary, but borrowers are commonly asked to provide evidence of their income, debts, assets and proposed purchase.
A typical application may involve:
- Identification documents
- Recent payslips
- Employment details
- Bank statements
- Existing mortgage statements
- Personal loan and credit card details
- Evidence of savings
- Rental statements for existing properties
- Rental appraisal for the proposed purchase
- Contract of sale, where applicable
Self employed applicants may also need business tax returns and financial statements.
Preparing this information early can make it easier to identify issues before submitting a formal application.
What Happens If Your Investment Loan Doesn’t Pass Serviceability?
If an application doesn’t satisfy the lender’s serviceability requirements, the lender may offer a lower borrowing amount or decline the application.
The next step should be understanding the specific reasons.
For example, the issue may relate to existing debt, the treatment of variable income or the lender’s assessment of rental income.
A lower purchase budget may be appropriate.
Alternatively, another suitable lender may assess the circumstances differently.
It’s important not to assume that every decline can be overcome by applying elsewhere.
If the underlying financial position cannot comfortably support the proposed borrowing, increasing debt may not be appropriate.
A considered review can help establish whether to revise the borrowing amount, improve financial readiness or delay the purchase.
How Serviceability Affects Investors Building a Property Portfolio
Investment loan serviceability can become increasingly important as investors acquire additional properties.
Each purchase may add another mortgage and potential rental income source.
However, additional rent doesn’t necessarily offset the full amount of the new assessed debt.
An investor may eventually reach a point where further borrowing becomes difficult under lender assessment requirements.
This is sometimes described as reaching a serviceability limit.
Having substantial equity doesn’t automatically resolve the issue because equity and repayment capacity are assessed separately.
Investors intending to purchase multiple properties may benefit from considering their longer term borrowing strategy before selecting individual loan arrangements.
For a broader assessment of financial readiness, read Can I Afford an Investment Property? A Finance Readiness Guide.
Frequently Asked Questions
What Does Serviceability Mean for an Investment Loan?
Serviceability is a lender’s assessment of whether you can afford the proposed loan repayments alongside existing debts and living expenses, using acceptable income and applicable lending criteria.
How Do Banks Calculate Investment Loan Serviceability?
Lenders assess acceptable income, rental income, living expenses, existing liabilities and repayments on the proposed loan. They generally apply interest rate assessment requirements and other credit policies.
Do Banks Count 100% of Rental Income?
Usually not. Many lenders adjust eligible rental income to account for vacancy and property related risks. The assessment method varies between lenders.
Can Rental Income Increase My Borrowing Capacity?
Yes, eligible rental income may contribute to borrowing capacity. However, lenders also account for existing debt, property expenses and their own rental income policies.
Does Having More Equity Improve Serviceability?
Not automatically. Equity may help satisfy deposit or security requirements, but lenders must still determine whether you can repay the additional borrowing.
Why Is My Investment Borrowing Capacity Lower Than Expected?
Possible reasons include existing mortgage commitments, household expenses, rental income adjustments, credit card limits and higher assessed repayments under lender serviceability rules.
Can Self Employed Applicants Get Investment Loans?
Yes, subject to lender approval. Self employed applicants may need to provide business financial statements, tax returns and other income verification documents.
Can I Get Another Investment Property Loan If I Already Have Two Mortgages?
Potentially. The lender will assess your existing mortgage obligations, eligible rental income, other debts and overall repayment capacity before considering additional borrowing.
Is the 3% Serviceability Buffer the Interest Rate I Will Pay?
No. The buffer is used in the lender’s assessment of repayment capacity. Your actual interest rate is determined by the approved loan arrangement.
Understand Your Investment Borrowing Capacity with NMC Finance
Investment loan serviceability can be difficult to estimate without understanding how lenders assess income, rental properties and existing financial commitments.
Two borrowers with similar incomes may have very different borrowing options, and different lenders may assess the same application differently.
At NMC Finance, we help Australian property investors understand lender requirements, review borrowing capacity and compare suitable investment loan options.
Our approach considers your current financial circumstances alongside your longer term property investment plans.
Whether you’re purchasing your first investment property, refinancing an existing loan or considering another addition to your portfolio, understanding your serviceability is an important starting point.
Want to understand how much you may be able to borrow?
Explore our Property Investor Loans page to learn more about investment finance options and arrange a conversation with the NMC Finance team.
Disclaimer: This article provides general information only and does not constitute personal financial, investment, taxation or legal advice. All examples are illustrative. Lending criteria and regulatory requirements may change, and all finance is subject to lender assessment and approval.